GDP Is Up. Corporate Profits Are Soaring. But Are American Households Better Off?


The latest U.S. economic numbers look encouraging. Real GDP grew at an annualized 2.2% in the second quarter of 2026, significantly higher than the previous 1.5% estimate. On its face, that suggests an economy performing better than expected. But another number deserves just as much attention: corporate profits from current production increased by $384 billion during the same quarter. Those two figures together tell us the economy is producing more and corporate America is doing exceptionally well. They do not necessarily tell us that American households are doing better.
That distinction is increasingly important because GDP measures economic production, not household financial security. It does not tell us how much money remains after a family pays for housing, food, insurance, utilities and transportation. Consumer spending can increase even when household finances deteriorate because people cannot simply stop buying groceries, driving to work, paying insurance or keeping the electricity on. Spending more, therefore, should not automatically be interpreted as becoming more prosperous.
Fuel Prices Show the Disconnect
Fuel provides one of the clearest examples. The national average for regular gasoline is approximately $4.43 per gallon, compared with $3.15 a year ago. Diesel now averages approximately $6.41 nationally, compared with $3.70 a year ago—an increase of roughly 73%. The importance of diesel extends far beyond the person standing at a fuel pump. It moves tractor-trailers carrying groceries and consumer products, powers agricultural and construction equipment, supports commercial fleets and touches substantial portions of the nation's distribution infrastructure. When diesel becomes dramatically more expensive, those additional costs move throughout the supply chain until businesses absorb them, increase prices or do some combination of both.
That makes the recent profitability of major energy companies particularly noteworthy. ExxonMobil reported $14.5 billion in Q2 earnings, more than double the $7.1 billion reported a year earlier. Chevron reported $12.1 billion while also reporting record U.S. production and record crude throughput at its U.S. refineries. Valero Energy reported $3.7 billion in net income compared with just $714 million during Q2 2025—more than five times the previous year's result.
Those results alone do not establish artificial price manipulation. Crude prices, refinery capacity, inventories, transportation, geopolitical events and other market conditions all influence fuel prices. But they do raise an important economic question. If extraordinarily high prices are primarily the unavoidable consequence of higher costs, how are some of the companies supplying those necessities simultaneously producing extraordinary increases in profit? The question isn't whether corporations should earn profits; profitability is fundamental to business. The question is how much of the increasing cost being absorbed by households represents unavoidable economic pressure and how much is being converted into expanding corporate margins.
The Pattern Extends Beyond Energy
The same question becomes interesting when we look beyond oil and refining. Walmart's quarterly net sales increased 5.9%, while operating income increased 28.8% to approximately $9.4 billion. Walmart's performance has multiple causes and cannot simply be attributed to higher consumer prices, but the disparity illustrates why corporate profitability deserves a place alongside GDP and consumer spending when evaluating the health of the economy.
There is nothing inherently problematic about a company becoming more efficient or profitable. But when corporate earnings and margins are expanding substantially while households continue confronting elevated prices for necessities, we should be careful about using aggregate economic growth as shorthand for widespread prosperity. An economy can perform very well for corporations, investors and particular sectors without producing the same improvement in household purchasing power.
A Growing GDP Economy and a Healthy Household Are Not the Same Thing
That may be the most important lesson contained within the latest GDP report. The 2.2% growth figure isn't false, nor does it need to be dismissed to recognize what it doesn't measure. GDP can rise, corporate profits can soar and consumer spending can increase while household financial capacity simultaneously deteriorates. A household spending more because necessities consume a larger portion of its income is in a fundamentally different economic position from a household spending more because its income and discretionary purchasing power have increased.
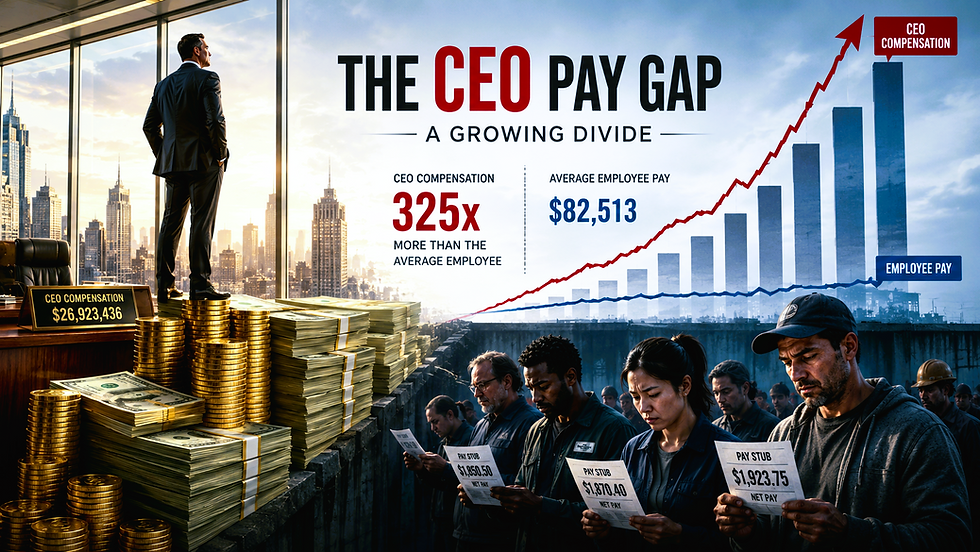
Perhaps, then, the more meaningful question isn't simply whether the economy is growing. It is who is benefiting from that growth and whether household purchasing power is growing with it. When economic performance is evaluated primarily through production, spending and corporate earnings, we risk overlooking the financial condition of the people ultimately paying for much of that activity.
Economic conditions like these are also why long-term planning cannot depend solely upon today's visible indicators. QSF Pathway Intelligence examines hidden constraints, delayed triggers, competing pressures and the unknown unknowns capable of changing a financial pathway over time. Fuel shocks, changing corporate pricing behavior and declining household purchasing power can appear manageable individually while their combined effects gradually alter the viability of a long-term plan. Identifying those emerging conditions earlier gives individuals and households a clearer understanding of how decisions made today may perform in the economic environment they encounter tomorrow.

Comments